Table of Contents
Managing money wisely is one of the most important responsibilities for every family. In 2026, rising living costs, changing financial needs, and unexpected expenses make proper financial planning more important than ever. Therefore, families need practical strategies to manage income, control expenses, build savings, and prepare for the future.
Whether you are planning to buy a home, save for your children’s education, prepare for retirement, or simply improve your monthly finances, following the right financial planning tips can help you make better decisions. Moreover, a well-organized financial plan gives your family greater confidence and reduces financial stress.
In this article, we discuss 10 smart financial planning tips that can help families build a stronger and more secure financial future in 2026.
Why Financial Planning Is Important for Every Family
Financial planning is not only about saving money. Instead, it involves managing your income, expenses, savings, investments, insurance, and debts in a structured way. As a result, families can achieve both short-term needs and long-term goals.
Furthermore, good financial planning helps you prepare for unexpected situations. It also allows you to make informed decisions when taking a home loan, investing money, or planning for retirement.
Now, let’s look at the most useful financial planning tips every family can follow.
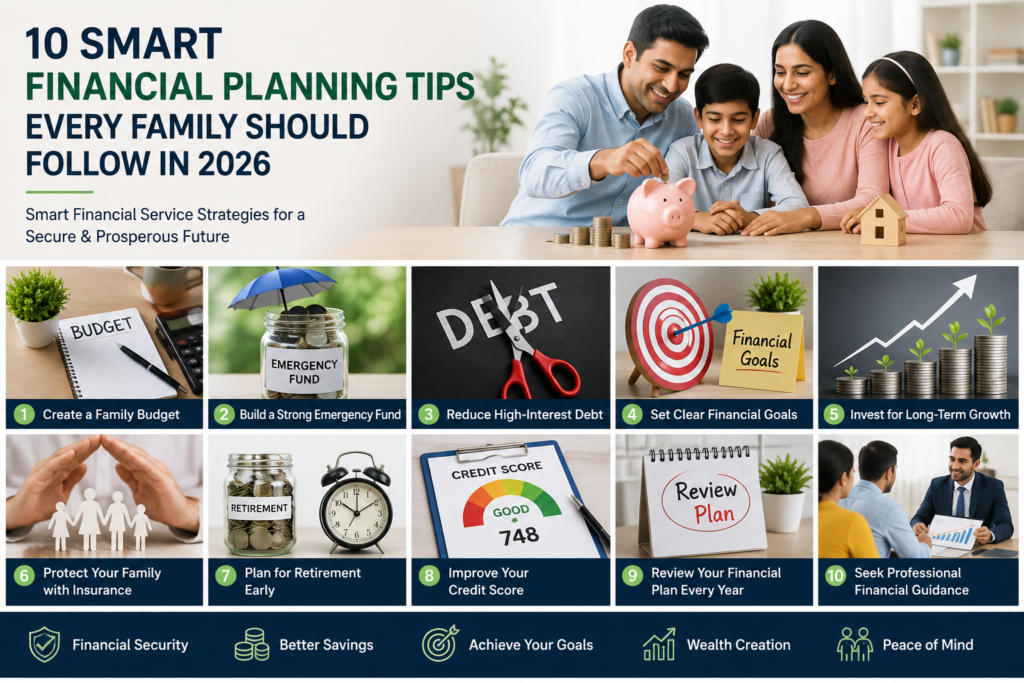
1. Create a Realistic Monthly Family Budget
The first step toward financial stability is creating a practical monthly budget. Start by calculating your total household income. Then, list your regular expenses, including rent or home loan EMIs, groceries, education, transportation, utilities, and other essential costs.
After that, separate necessary expenses from non-essential spending. Consequently, you can identify areas where you may be spending unnecessarily.
A simple budget allows your family to understand where money goes each month. Therefore, make budgeting a regular habit and review your expenses at the end of every month.
2. Build an Emergency Fund
Unexpected expenses can affect even a carefully prepared family budget. Medical expenses, job changes, urgent home repairs, or other emergencies can require immediate financial support.
For this reason, building an emergency fund should be one of your most important financial planning tips. Ideally, families should work toward maintaining enough savings to cover several months of essential expenses.
Start with a small monthly contribution if necessary. Over time, these regular savings can create a valuable financial safety net.
3. Reduce and Manage Your Debt
Debt can become a major financial burden when it is not managed properly. High-interest credit card balances and unnecessary loans can reduce the amount of money available for savings and investments.
Therefore, make a plan to reduce expensive debt. Pay your EMIs and credit card bills on time and avoid borrowing money for unnecessary purchases.
Additionally, before taking a new loan, compare the interest rate, repayment period, processing charges, and other costs. This is one of the practical financial planning tips that can help families maintain better financial control.
4. Set Clear Financial Goals
Saving without a specific goal can make it difficult to stay motivated. Instead, create clear financial objectives for your family.
Your goals may include:
- Buying a home
- Children’s education
- Building an emergency fund
- Starting a business
- Planning family travel
- Preparing for retirement
Next, assign a target amount and expected timeline to each goal. As a result, you can create a more organized savings and investment plan.
5. Start Investing for Long-Term Goals
Saving money is important; however, long-term wealth creation may require appropriate investments. Depending on your financial goals, risk tolerance, and time horizon, you can explore different investment options.
For example, families may consider fixed deposits, mutual funds, government-backed schemes, bonds, or other suitable investment products.
However, do not invest simply because an option is popular. Instead, understand the risks and potential returns before making a decision. If necessary, seek qualified professional guidance.
Starting early is another valuable point among these financial planning tips because it gives your money more time to potentially grow.
6. Protect Your Family with Appropriate Insurance
Financial planning should also include protection against unexpected risks. A sudden medical emergency or loss of income can significantly affect a family’s finances.
Therefore, consider suitable health and life insurance based on your family’s circumstances. Insurance can help protect your savings from being exhausted by unexpected expenses.
Furthermore, review your coverage periodically because your financial responsibilities can change as your family grows.
7. Plan for Your Children’s Education
Education is an important long-term expense for many families. Since education costs can increase over time, starting early can make the financial burden easier to manage.
First, estimate the future cost of education. Then, determine how much you need to save regularly to reach the target.
You can also create a separate education fund rather than mixing it with your everyday savings. This approach makes your progress easier to track and supports better financial discipline.
8. Prepare for Retirement Early
Retirement planning should not be postponed until the final years of your career. Instead, begin planning as early as possible.
Determine your expected retirement expenses, consider inflation, and estimate how much you may need in the future. Then, create a suitable long-term savings and investment strategy.
Starting early can make retirement planning more manageable because you have more time to build your savings. Thus, retirement planning remains one of the essential financial planning tips for working families.
9. Maintain a Healthy Credit Score
Your credit history can influence your ability to obtain loans and may affect the terms offered by lenders. Therefore, maintaining a healthy credit profile is an important part of financial management.
Pay your loan EMIs and credit card bills on time. Also, avoid taking unnecessary credit and monitor your credit report periodically.
A strong credit profile can be especially useful when you plan to apply for a home loan or another major financial facility.
10. Review Your Financial Plan Every Year
Your financial situation does not remain the same forever. Income, expenses, family responsibilities, investments, and goals can change over time.
Therefore, review your financial plan at least once a year. Check your savings, investments, insurance coverage, debts, and financial goals. If your income increases, consider increasing your savings and investments as well.
Regular reviews ensure that your plan remains relevant and effective. Consequently, this final point completes our list of financial planning tips for families in 2026.
Common Financial Planning Mistakes Families Should Avoid
Even with a good income, poor financial decisions can create unnecessary difficulties. Therefore, families should avoid common mistakes such as:
- Spending more than the monthly income
- Ignoring emergency savings
- Delaying retirement planning
- Taking unnecessary loans
- Investing without understanding risk
- Missing EMI or credit card payments
- Failing to review insurance coverage
- Not setting specific financial goals
By avoiding these mistakes, families can create healthier financial habits and improve their long-term financial stability.
How Professional Financial Guidance Can Help
Managing finances independently can sometimes become complicated. Home loans, investments, insurance, and long-term financial goals all require careful consideration.
A professional financial consultancy can help families understand available options and make informed decisions based on their individual requirements. In addition, experienced advisors can assist with financial planning, loan guidance, and other financial solutions.
For families looking for personalized support, professional advice can complement these financial planning tips and help create a more structured financial roadmap.
Conclusion: Build a Secure Financial Future in 2026
Financial security begins with small and consistent decisions. By creating a budget, building an emergency fund, managing debt, investing wisely, protecting your family, and planning for future goals, you can develop a stronger financial foundation.
Most importantly, financial planning should be an ongoing process rather than a one-time activity. Review your progress regularly and make adjustments whenever your family’s circumstances change.
Following these financial planning tips can help your family manage money more effectively and work toward important goals such as home ownership, children’s education, and a comfortable retirement.
At Axion Core Consultancy, we provide professional financial guidance and home loan assistance to help clients make informed financial decisions. With the right planning and professional support, your family can take confident steps toward a more secure financial future in 2026.
Frequently Asked Questions About Financial Planning
What is the first step in family financial planning?
Creating a realistic monthly budget is a good starting point. It helps you understand your income, expenses, savings capacity, and financial priorities.
How much should a family keep as an emergency fund?
The appropriate amount depends on your income and expenses. Many families aim to build savings that can cover several months of essential living costs.
Why is retirement planning important?
Starting retirement planning early gives you more time to save and potentially benefit from long-term investment growth. Therefore, it should be included in your overall financial strategy.
Should families seek professional financial advice?
Professional guidance can be useful when making complex decisions involving investments, loans, insurance, and long-term financial goals. A qualified advisor can help you understand suitable options based on your circumstances.